ClickCease
Abbotsford private mortgage lender

Private Mortgage Lender in Abbotsford

Private mortgage financing can be useful when the property, credit profile, income structure, mortgage position, or timing does not fit a standard bank approval.

Seven Lending helps Abbotsford homeowners, buyers, and property investors review private first and second mortgage structures based on the real estate, available equity, lender-accepted value, payment plan, costs, and exit strategy.

Abbotsford stands apart from many Lower Mainland markets because urban neighbourhoods sit alongside acreages, ALR parcels, agricultural properties, and floodplain areas. Those property details can change the appraisal, lender pool, maximum leverage, insurance requirements, and exit options.

  • Private first and second mortgage structures only.
  • Urban residential, rural acreage, ALR, and select agricultural property review.
  • LTV, lender conditions, fees, secured-loan risks, and exit planning explained before closing.
First or Second Position The mortgage position is reviewed before pricing because it changes lender risk and available leverage.
Property-Specific Underwriting Acreage, ALR, strata, rural, and floodplain properties can require different appraisal and lender criteria.
Exit Before Funding A private mortgage should have a defined repayment route and a backup plan before the term begins.
Abbotsford property owners reviewing a private first or second mortgage
Private lending in Abbotsford

What a Private Mortgage Lender Reviews

A private mortgage is secured against real estate. The lender may use a more property-focused review than a conventional bank, but flexible underwriting does not mean that credit, income, title, insurance, or repayment ability are ignored.

The first questions are usually practical: What property secures the mortgage? What is the accepted value? What debt is already registered? Will the new mortgage be first or second position? Why are the funds needed? How will the balance be repaid?

For the provincial overview of private lending structures, see private mortgage lenders in BC.

LTV = total mortgage debt ÷ lender-accepted property value × 100
Local property expertise

Abbotsford Property Types Need Different Private-Lender Reviews

The city includes conventional residential neighbourhoods as well as a large agricultural and rural land base. A private lender's comfort with the property can be just as important as the borrower's credit profile.

Clearbrook & Central Abbotsford

Urban Residential

Detached homes, townhomes, and strata properties are commonly supported by standard residential appraisals, but condition, tenancy, strata issues, and marketability still matter.

East Abbotsford & Whatcom

Hillside and Larger Residential Lots

Topography, access, retaining structures, renovations, lot characteristics, and comparable sales can affect the lender's valuation and security review.

Bradner & Mount Lehman

Rural Acreage

Acreage files may require closer review of land size, residence quality, outbuildings, wells or septic systems, access, agricultural use, and resale demand.

Matsqui Prairie

Agricultural and ALR Context

ALR status, zoning, permitted use, farm improvements, residence value, access, appraisal support, and marketability can narrow the lender pool.

Sumas Prairie

Floodplain and Agricultural Property

Lenders can look closely at flood exposure, insurance availability, improvements, access, drainage context, appraisal assumptions, and the property's resale market.

Townline & West Abbotsford

Residential and Rental Files

Rental use, suite income, occupancy, property condition, current mortgage balances, and the exit strategy can affect a private first or second mortgage review.

Mortgage position

Private First Mortgage vs Private Second Mortgage

These are not interchangeable structures. Mortgage position changes the lender's security, pricing, available proceeds, and repayment risk.

First position

Private First Mortgage

A private first mortgage is registered ahead of other mortgages. It can support a purchase or replace an existing first mortgage through a refinance.

  • The lender holds the first mortgage claim on the property.
  • Existing secured debt may be paid out at closing.
  • Prepayment or discharge costs on the current mortgage can reduce net funds.
  • The lender still reviews property value, title, taxes, insurance, payment plan, and exit.
Second position

Private Second Mortgage

A second mortgage is registered behind the current first mortgage. It may provide a defined amount of capital without replacing that first charge.

  • The first lender is paid before the second lender if enforcement occurs.
  • The lender reviews combined LTV using both mortgage balances.
  • Second-position pricing can be higher because the lender accepts more security risk.
  • A refinance, sale, or other repayment event should be planned before maturity.

Learn how a second mortgage works.

ALR, rural & acreage underwriting

Why Abbotsford Rural Properties Need a More Detailed Review

Much of Abbotsford's land base is agricultural, and rural property security can be harder to compare than a standard city-lot home. The lender may need to understand both the residence and the land that supports the mortgage.
ALR and zoning status The lender may confirm whether the parcel is in the ALR, what uses are permitted, and whether current improvements fit the property record.
Acreage and land contribution The lender may treat the residence, usable acreage, farm improvements, and excess land differently when deciding value and leverage.
Access and services Road access, water source, septic system, utilities, and year-round usability can influence marketability.
Buildings and improvements Barns, shops, greenhouses, secondary residences, and other structures may need to be documented and supported by the appraisal.
Insurance and flood context On Sumas Prairie and other low-lying areas, insurance availability and flood-related property information can affect lender comfort.
Exit market A future refinance or sale depends on who can finance the property later, not only on today's private mortgage approval.
Local context: Abbotsford's agricultural land base and Sumas Prairie flood exposure make property-level due diligence especially important on rural and acreage files.
Rural acreage and ALR property considered for a private mortgage in Abbotsford
Private mortgage scenarios

When an Abbotsford Private Mortgage May Be Considered

The file should solve a specific property-secured problem. These scenarios remain private-mortgage focused rather than expanding into unrelated financing products.

Bank-Declined Purchase

A buyer has a suitable property and down payment, but income, credit, or timing prevents a conventional approval.

Maturing First Mortgage

A current mortgage is reaching maturity and the borrower needs a defined period to improve the file or prepare another exit.

Second Mortgage Behind a Strong First

The borrower wants to preserve the existing first mortgage while accessing a smaller amount of property-secured capital.

Rural or ALR Property

The property does not fit a standard urban lender because of acreage, agricultural use, ALR status, buildings, or resale considerations.

Recent Credit Event

The borrower has a recent credit problem, but the property, equity, payment plan, and exit may support a short-term private mortgage.

Time-Sensitive Property Payout

The borrower needs to resolve a secured payout or closing deadline and has enough property strength for a lender to review the request.

Qualification

What a Private Lender Usually Needs to See

Flexible underwriting still requires enough information to understand the property, security, borrower risk, and repayment route.

Property and Security

  • Accepted property value or appraisal
  • Current mortgage balances and registered charges
  • First or second mortgage position
  • Property taxes and insurance
  • Title, zoning, occupancy, and legal use
  • ALR, acreage, farm, or floodplain information when relevant

Borrower and Exit

  • Requested mortgage amount and loan purpose
  • Payment source during the term
  • Credit history and explanation of recent events
  • Income or cash-flow support requested by the lender
  • Target refinance, sale, or other repayment event
  • Backup plan if the first exit takes longer than expected
Private mortgage terms fees and risk review for an Abbotsford property
Cost and risk

Private Mortgage Rates, Fees, Net Funds, and Risk

Private mortgages generally cost more than conventional long-term bank financing. The decision should be based on the total borrowing cost and whether the short-term mortgage has a realistic exit.

Interest and APR Review the contract rate together with the cost-of-borrowing disclosure.
Lender and service fees Fees can vary by mortgage position, LTV, property type, loan size, term, and complexity.
Appraisal and legal costs Closing can include valuation, legal registration, title insurance, payouts, and discharge work.
Interest-only payments A lower monthly payment can leave the full principal outstanding at maturity.
Prepayment and extension Early payout or an extension can have lender-specific rules, costs, or fresh approval requirements.
Net funds The amount received is the approved mortgage less existing payouts and all disclosed closing deductions.
Secured-loan risk: a private mortgage is registered against real estate. Missed payments or an unpaid maturity balance can create added costs and enforcement risk.

Review private mortgage pricing factors.

Proof before commitment

Private Mortgage Trust Signals to Verify

Proof comes from the transaction documents and property review, not from generic promises about speed or approval.

The lender is identified The written commitment should identify the lender or lending entity and the mortgage position being offered.
The property value is supported The lender should use an accepted appraisal or another valuation method it considers sufficient for the file.
The LTV math is clear Existing secured debt, the proposed mortgage, and the lender-accepted value should support the stated leverage.
The full costs are written Rate, APR or cost of borrowing, lender fees, applicable service fees, appraisal, legal costs, and expected net funds should be reviewable.
Legal closing is separate Registration, title, payouts, borrower signing, and release of funds are completed through the legal closing process.
The exit has dates A refinance, sale, or other repayment route should include a target timeline and backup plan before funding.

Use the private lender safety checklist before accepting a private mortgage commitment.

Private mortgage process

How an Abbotsford Private Mortgage Moves From Review to Funding

A clear file lets the lender focus on the property, leverage, conditions, and repayment plan instead of chasing missing information.

Property Review

Share the address, property type, estimated value, current secured balances, requested amount, purpose, and deadline.

Lender Fit and Terms

The file is assessed for first or second position, LTV, property eligibility, pricing, required conditions, and the proposed exit.

Appraisal and Conditions

The lender may request valuation, insurance, title, tax, income, rural property, ALR, lease, or other supporting documents.

Legal Closing and Exit Tracking

After conditions are satisfied, the mortgage closes legally. The refinance, sale, or other repayment plan should be monitored before maturity.

See the private mortgage review process for the next steps after submitting a file.

Common questions

FAQ

Can an ALR property in Abbotsford qualify for a private mortgage?

Possibly. The lender may review ALR status, permitted use, zoning, residence and farm improvements, appraisal support, access, insurance, mortgage position, LTV, marketability, loan purpose, and exit strategy. ALR status alone does not guarantee approval or decline.

Can a rural acreage property be considered?

Some private lenders consider acreage properties. The residence, land size, excess acreage, outbuildings, water and septic systems, road access, legal use, appraisal evidence, and resale market can affect the decision.

Can a Sumas Prairie property be financed privately?

Some lenders may review Sumas Prairie properties. Flood exposure, insurance availability, property improvements, access, appraisal assumptions, mortgage position, LTV, and marketability can influence lender eligibility.

What is the difference between a private first and second mortgage?

A first mortgage is registered ahead of other mortgages. A second mortgage sits behind the first lender. Because the second lender has less security priority, the allowed leverage, rate, fee, and conditions can differ.

Is there one maximum LTV for every Abbotsford private mortgage?

No. Maximum LTV varies by lender, property type, location, first or second position, marketability, loan size, borrower circumstances, and exit strength. Rural, ALR, agricultural, or floodplain files may be reviewed more conservatively.

What happens if I cannot repay at maturity?

An extension or refinance is not guaranteed. Delays can create new fees, a higher rate, fresh appraisal requirements, or enforcement risk. A detailed private mortgage exit strategy should be prepared before funding.

Abbotsford private mortgage review

Get Your Abbotsford Private Mortgage File Reviewed

Prepare the property address, estimated value, current mortgage balances, requested amount, purpose, preferred timing, and expected repayment route.

For rural, acreage, ALR, or Sumas Prairie properties, include zoning or property-use information, access, buildings, insurance details, and any recent appraisal you already have.

Before accepting a private mortgage

  • Confirm the lender and mortgage position.
  • Confirm the lender-accepted property value and LTV.
  • Review rate, APR, fees, payment amount, maturity date, and net funds.
  • Understand appraisal, title, insurance, and legal conditions.
  • Confirm prepayment, extension, and enforcement terms.
  • Have a target exit date and backup route.
Read Our Client Success Stories

Meet Our Team

Our team is made up of dedicated professionals who are passionate about helping our clients succeed. We are proud to be your neighbours and your trusted advisors.

Raghav Side Hand Crossed

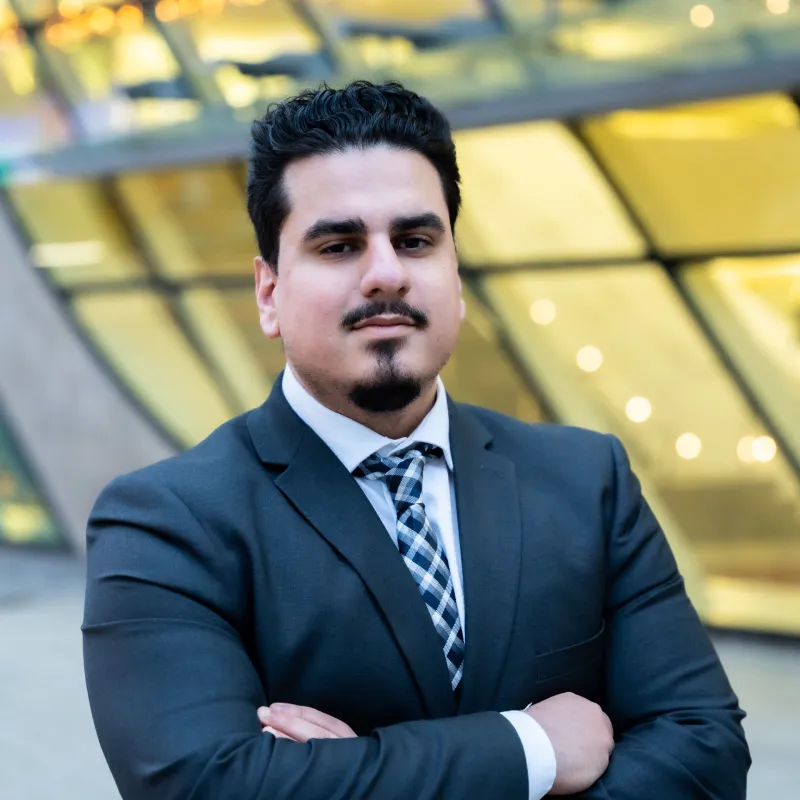
Raghav Manchanda

Managing Broker

The visionary behind Seven Lending, our Managing Broker oversees all lending operations and ensures regulatory compliance. With a deep understanding of the private mortgage market, he focuses on risk management and strategic growth. He mentors the team while fostering high-level relationships with institutional partners, ensuring every transaction aligns with our core values of integrity and efficiency.

Darius

Darius Hossein-pour

Business Development Manager (BDM)

Our BDM is the primary bridge between Seven Lending and the broker community. He focuses on expanding our network, identifying new market opportunities, and providing creative structuring for complex private deals. Known for his responsiveness and industry insights, he ensures that our lending products meet the evolving needs of our partners and their clients.

Simran

Simran Attili

Mortgage Broker

Our Mortgage Broker is a dedicated client advocate, specializing in custom private lending solutions. She manages the end-to-end application process, expertly navigating unique financial scenarios to secure the best possible terms. By prioritizing clear communication and fast turnaround times, she helps borrowers bridge financial gaps and achieve their real estate goals with confidence.

Gagan Side

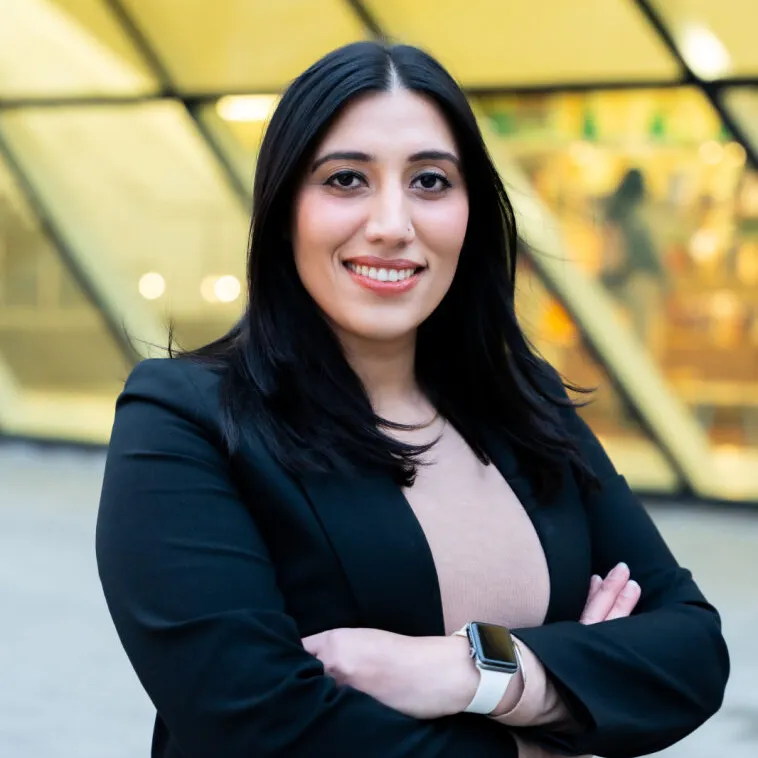
Gagandeep Kaur

Mortgage Underwriter

She works with precision and speed. She is responsible for evaluating loan applications, assessing property valuations, and analyzing risk to ensure sound lending decisions. By working closely with brokers and BDM, she streamlines the approval process. For her, underwriting isn’t just about checking boxes—it’s about providing the clarity and speed you need to move forward with your real estate goals.

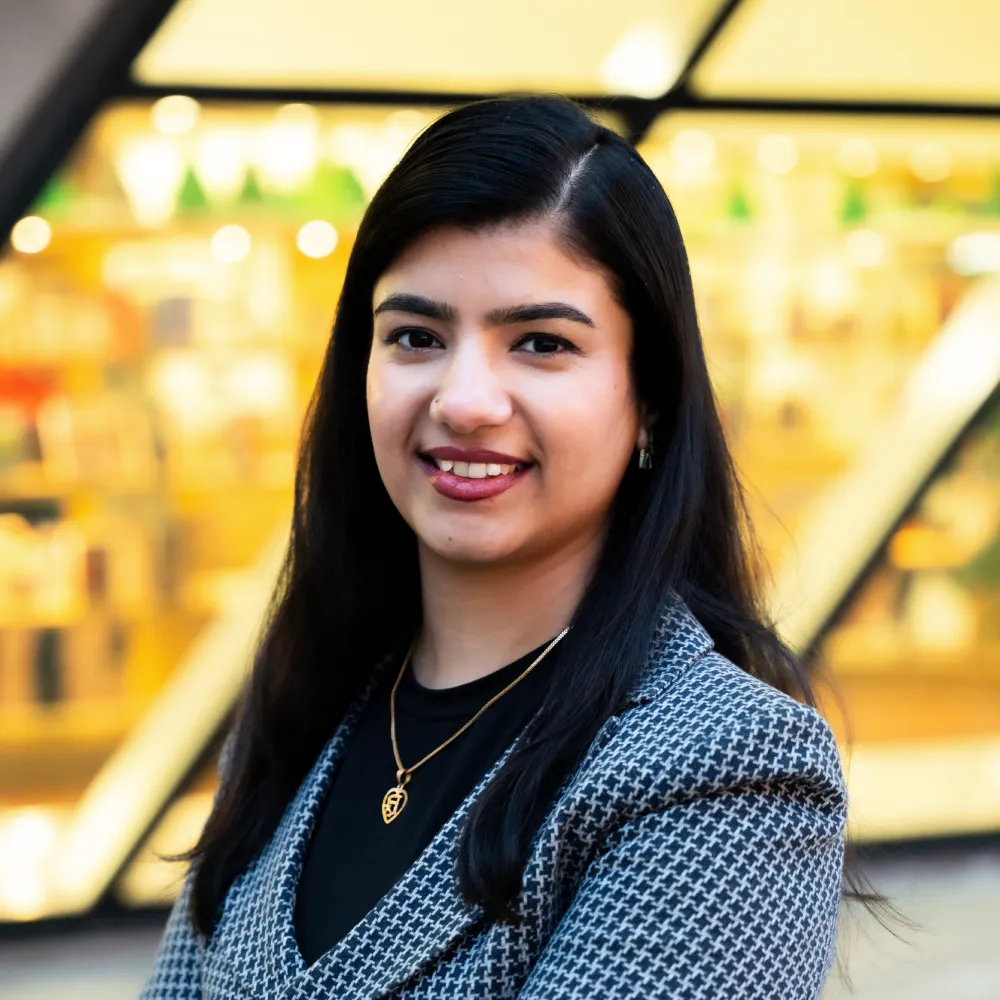
Pranika

Pranika Khanna

Administrative Assistant & Social Media Coordinator

As the creative spark and organizational anchor of Seven Lending, our Administrative Assistant and Social Media Coordinator ensure our office runs like clockwork while our brand shines online. She is the voice of our digital community, crafting engaging content that demystifies private lending. Whether streamlining logistics for a smooth closing or sharing industry insights, she makes the mortgage process feel less like paperwork and more like a shared success story.

Abbotsford Private Mortgage Solutions

Private Mortgage Brokers in Abbotsford, BC

When conventional mortgage requirements do not fit your property, income, credit history, or deadline, an Abbotsford private mortgage broker can help you assess another route.

Seven Lending arranges private first and second mortgages for Abbotsford homeowners, buyers, investors, and business owners. We review the complete file and compare available options from private and alternative lenders.

We explain rates, fees, conditions, and risks before you decide. All financing is subject to lender approval.

First and Second Mortgages

Compare a full private first mortgage with a second mortgage that may leave an existing first charge in place.

Property and Equity Review

Property value matters, but mortgage position, payment ability, marketability, and the exit plan also influence the decision.

Short-Term Planning

A private mortgage should solve a defined problem and include a realistic route to refinance, repayment, or sale.

Abbotsford homeowner reviewing private mortgage options with a broker
Understanding Available Equity

How Home Equity Financing Works in Abbotsford

Available equity is not simply the difference between an estimated property value and the current mortgage. A lender may also consider the permitted loan-to-value, all secured balances, mortgage position, property marketability, requested amount, payment plan, and exit strategy.

General estimate: permitted loan-to-value amount minus existing secured balances.

An appraisal and lender review may be required. An online estimate is not an approval or commitment.

Four Core Structures

Private Mortgage Options Our Abbotsford Brokers Can Arrange

The right structure depends on what must be solved, the existing mortgages, the cost of changing them, and the plan for repaying the private loan.

Private First Mortgages

For a purchase, renewal, or refinance where the private lender will hold the first registered charge.

Explore private mortgages →

Private Second Mortgages

For accessing equity while potentially leaving a favourable existing first mortgage in place.

Compare second mortgages →

Need help with debt consolidation, non-traditional income, an investment property, construction, or another equity-based request? Review all mortgage solutions →

When Banks Do Not Fit

When a Private Mortgage May Make Sense

Private mortgage lending is generally a short-term response to a specific qualification or timing problem—not a default replacement for lower-cost conventional financing.

Denied Renewal or Refinance

A lender change, income disruption, or recent credit issue may prevent a conventional renewal or refinance.

Urgent Closing Deadline

A purchase, payout, or refinance may need a faster review when conventional processing cannot meet the deadline.

Self-Employed Income

Business, seasonal, or non-traditional income may require alternative documentation and a different underwriting approach.

Credit or Arrears

Some private lenders consider impaired credit when the property, equity, payment plan, and exit strategy support the request.

Rental Property Financing

Investors may use private financing to close, refinance, renovate, or stabilize a rental before moving to longer-term funding.

Debt Restructuring

Secured financing may consolidate higher-interest balances, but total cost and the risk to the property must be considered.

Abbotsford Property Context

Properties Private Mortgage Lenders May Review

Abbotsford includes suburban homes, strata properties, rural acreages, agricultural land, and commercial buildings. Our brokers identify lenders whose property guidelines may fit; property eligibility is never guaranteed by location alone.

Detached homes and townhouses
Condos and strata properties
Rental and multi-unit properties
Rural acreages and some ALR properties
Industrial, retail, and mixed-use properties
Renovation and construction files

We review requests involving Clearbrook, Townline Hill, East Abbotsford, Whatcom, Matsqui, Bradner, Mount Lehman, Sumas Prairie, and other Abbotsford areas. Every property is assessed on its own merits.

ALR, rural, or floodplain property: possible financing depends on title, zoning and permitted use, buildings, appraisal, access, insurance, marketability, environmental or flood considerations, loan purpose, and individual lender policy.

Residential properties considered for private mortgages in Abbotsford
Choosing the Mortgage Position

Bank, B-Lender, or Private Mortgage?

OptionOften Considered WhenPrimary Review
Bank mortgageThe borrower and property fit standard income, credit, and debt-service guidelines.Verified income, credit, down payment or equity, debt ratios, and property.
B-lender mortgageIncome or credit is outside prime-bank rules but the file supports an alternative institutional option.Broader income documents, credit explanation, property, equity, and affordability.
Private mortgageThe request is time-sensitive, equity-driven, short term, or outside institutional guidelines.Property, equity, mortgage position, payment ability, purpose, and exit strategy.
Qualification

What Our Brokers Prepare for Lender Review

  • Current property value supported by an appraisal or lender-approved valuation.
  • Existing secured balances and the proposed mortgage position.
  • Loan-to-value permitted for the property, location, and risk profile.
  • Property marketability, condition, use, and title structure.
  • Income and payment ability, using documentation accepted by the lender.
  • Credit history and explanation, not only a single score.
  • Loan purpose and exit strategy before the short term ends.
Documents

What You May Need

  • Government-issued identification
  • Current mortgage statements
  • Property tax and insurance information
  • Purchase contract or payout statement, where applicable
  • Income or business documentation requested by the lender
  • Lease or rental information for investment properties
  • Current appraisal or property valuation

Requirements vary. “Alternative documentation” does not mean that every loan is available without income or affordability review.

Understand the Full Cost

Private Mortgage Rates, Fees, and Risks

Private mortgages generally cost more than conventional bank mortgages. Flexibility and speed must be weighed against the complete borrowing cost.

  • Rates vary by lender, mortgage position, loan-to-value, property, term, and risk.
  • Lender fees, applicable brokerage fees, legal expenses, appraisal costs, and discharge charges may apply.
  • Terms are often short, and renewal or extension is not guaranteed.
  • Prepayment privileges and penalties vary by commitment.
  • Missed payments can lead to enforcement and place the property at risk.
Review general private mortgage rate information →
Mortgage broker explaining private mortgage rates fees and risks
Plan the Way Out

Your Exit Strategy Comes Before Funding

A private mortgage should solve a defined short-term problem. The repayment route should be realistic before the loan closes.

Stabilize the File

Address the urgent closing, payout, arrears, or other financing pressure.

Improve the Weak Point

Rebuild credit, document income, resolve tax issues, or complete planned work.

Move to Better Financing

Refinance to a bank or B-lender when the borrower and property qualify.

Repay as Planned

Use a documented sale, refinance, or other credible liquidity event to repay.

Read our private mortgage exit strategy guide →

Clear Steps

How Seven Lending Arranges a Private Mortgage

Initial Review

Discuss the property, balances, requested amount, purpose, and deadline.

Document Review

Collect identification, mortgage statements, property details, and required supporting documents.

Lender Comparison

Review available lender terms, rates, fees, conditions, and exit requirements.

Legal Closing

If approved and accepted, the borrower’s lawyer completes registration and funding.

Brokerage Experience and Accountability

Meet the Team Serving Abbotsford Borrowers

Seven Lending is the operating name of Seven Capital Group Inc., registration #A0117454. Co-founder and Managing Broker Raghav Manchanda oversees the brokerage team, supported by mortgage, underwriting, and business-development professionals. The team serves Abbotsford from Seven Lending’s Surrey office; an Abbotsford office is not implied.

Learn more about Seven Lending and our team →

Raghav Manchanda, Managing Broker at Seven Lending

Raghav Manchanda

Managing Broker

Darius Hossein-pour, Business Development Manager at Seven Lending

Darius Hossein-pour

Business Development Manager

Simran Attili, Mortgage Broker at Seven Lending

Simran Attili

Mortgage Broker

Gagandeep Kaur, Mortgage Underwriter at Seven Lending

Gagandeep Kaur

Mortgage Underwriter

Pranika Khanna, Administrative Assistant at Seven Lending

Pranika Khanna

Administrative Assistant

Common Questions

Private Mortgage Broker FAQs for Abbotsford

What is a private mortgage in Abbotsford?

It is a mortgage secured by real estate and funded outside traditional banks. Private mortgages are commonly used for short-term financing problems when conventional guidelines do not fit. Rates, fees, terms, documents, and qualification requirements vary by lender.

Is Seven Lending the mortgage lender or the broker?

Seven Lending is a mortgage brokerage. We review the request and arrange financing through third-party lenders whose guidelines may fit. We do not guarantee approval, pricing, terms, or funding time.

Can I get a private mortgage with bad credit?

Some private lenders consider impaired credit when the property, equity, mortgage position, payment plan, and exit strategy support the request. Bad credit does not guarantee approval, and it can affect rates, fees, and conditions.

How much equity do I need?

There is no universal percentage. Permitted loan-to-value varies with the lender, mortgage position, property type, location, marketability, loan purpose, and complete risk profile. An appraisal may be required.

Can I keep my existing first mortgage?

Possibly. If there is sufficient room behind the existing first charge, a private second mortgage may provide funds without replacing it. The combined loan-to-value, first-mortgage terms, total payments, and costs must be reviewed.

Can a private mortgage broker help with an ALR property?

Potentially. A broker can identify lenders willing to review some agricultural and rural properties, but approval may depend on title, permitted use, zoning, buildings, appraisal, access, marketability, income, loan purpose, and the exit strategy. ALR status does not guarantee or automatically prevent financing.

Can a Sumas Prairie floodplain property be considered?

Some lenders may review floodplain properties. The appraisal, property improvements, insurance availability, flood-related requirements, mortgage position, loan-to-value, marketability, and individual lender policy can affect eligibility.

How quickly can a private mortgage close?

Timing varies with the lender, application completeness, appraisal, property, conditions, borrower documents, and legal closing. An initial review is not the same as final approval or funding.

What happens when the term ends?

The mortgage must be repaid, refinanced, renewed if the lender agrees, or discharged through a planned sale or other credible payout. Renewal and extension are not guaranteed, which is why the exit strategy should be established before funding.

Abbotsford borrower preparing to request a private mortgage review
Request a Review

Speak With a Private Mortgage Broker Serving Abbotsford

Share the property location, estimated value, existing mortgage balances, requested amount, financing purpose, and preferred deadline. Seven Lending will assess whether a private first mortgage, second mortgage, or another solution may fit.

Seven Lending is the operating name of Seven Capital Group Inc., registration #A0117454. Seven Lending is a mortgage brokerage serving Abbotsford and other BC communities from its Surrey office. All financing is subject to lender review and approval. Rates, fees, terms, conditions, property eligibility, and funding times vary.

Apply Now

*After submitting this form, we will contact you within 24 hours.

Start with Seven Lending. We Are Here For You!

*After submitting this form, we will contact you within 24 hours.

Start with Seven Lending. We Are Here For You!

*After submitting this form, we will contact you within 24 hours.