ClickCease
Kelowna private mortgage solutions

Private Mortgage Lenders in Kelowna for Flexible Property Financing

Private mortgage lenders in Kelowna may help when a bank cannot approve the property, income, credit profile, timing, or loan purpose under standard rules.

At Seven Lending, we review private first and second mortgage requests based on the property, available equity, mortgage position, loan-to-value ratio, costs, risks, and exit plan.

Kelowna files can involve strata homes, self-employed income, investment properties, construction projects, recreational properties, or short closing deadlines.

  • Private first and second mortgages for short-term needs.
  • Strata, investment, construction, and recreational property review.
  • Clear LTV, costs, risks, conditions, and exit planning.
Mortgage position

Private First and Second Mortgages in Kelowna

The mortgage structure should match the property, amount required, deadline, mortgage position, and expected repayment source.

First position

Private First Mortgage

A private first mortgage can support a purchase, refinance, maturing loan, or property that does not fit conventional lending. It becomes the primary charge on title.

  • Has priority on title.
  • May support a purchase or full refinance.
  • Existing secured debt may be paid out at closing.
Second position

Private Second Mortgage

A second mortgage sits behind the existing first mortgage. It may release equity without replacing the current first mortgage.

  • Combined LTV includes both mortgage balances.
  • May preserve the current first mortgage.
  • Needs a clear repayment or refinance plan.

Review how a second mortgage works →

Basic LTV formula: total secured mortgage debt ÷ lender-accepted property value. A lower LTV gives the lender a larger equity cushion, but it does not guarantee approval.
Kelowna property reviewed for private mortgage financing
Kelowna property review

What Shapes a Private Mortgage Decision

Each property type can change the appraisal, lender requirements, conditions, costs, and exit strategy.

The review may include property value, current mortgage balances, mortgage position, title, insurance, borrower cash flow, credit context, loan purpose, timing, and the planned route out of the short-term mortgage.

For self-employed borrowers, business records, bank deposits, contracts, or other reasonable income support may also be relevant.

Property context

Kelowna Property Scenarios We Review

Property-specific details affect valuation, marketability, conditions, and mortgage structure.

Strata Properties

Lenders may request strata fees, minutes, depreciation reports, insurance, special-assessment details, bylaws, and rental restrictions.

Recreational Properties

Seasonal access, water, septic, utilities, rental use, insurance, condition, and resale demand may narrow the available lender options.

Self-Employed Borrowers

Business owners, contractors, commission earners, and borrowers with variable income may need tax records, bank statements, contracts, or financial statements.

Recent Credit Events

The review may consider the property, available equity, cause of the credit issue, payment history, amount requested, and repayment plan.

Equity and LTV

Loan Position and Loan-to-Value in Kelowna

Mortgage position and LTV help determine the lender's security, the available loan amount, and the expected cost.

A first mortgage has priority on title. A second mortgage sits behind the first mortgage, so the lender reviews the combined balance of both loans against the accepted property value.

Property value alone does not determine the final mortgage amount. Property type, marketability, mortgage position, payment ability, costs, and exit planning can also affect the decision.

Kelowna property owner reviewing loan-to-value and mortgage position
Rates and costs

Private Mortgage Costs in Kelowna

Private mortgage pricing is file-specific. Compare the full cost of borrowing instead of relying on one advertised rate.

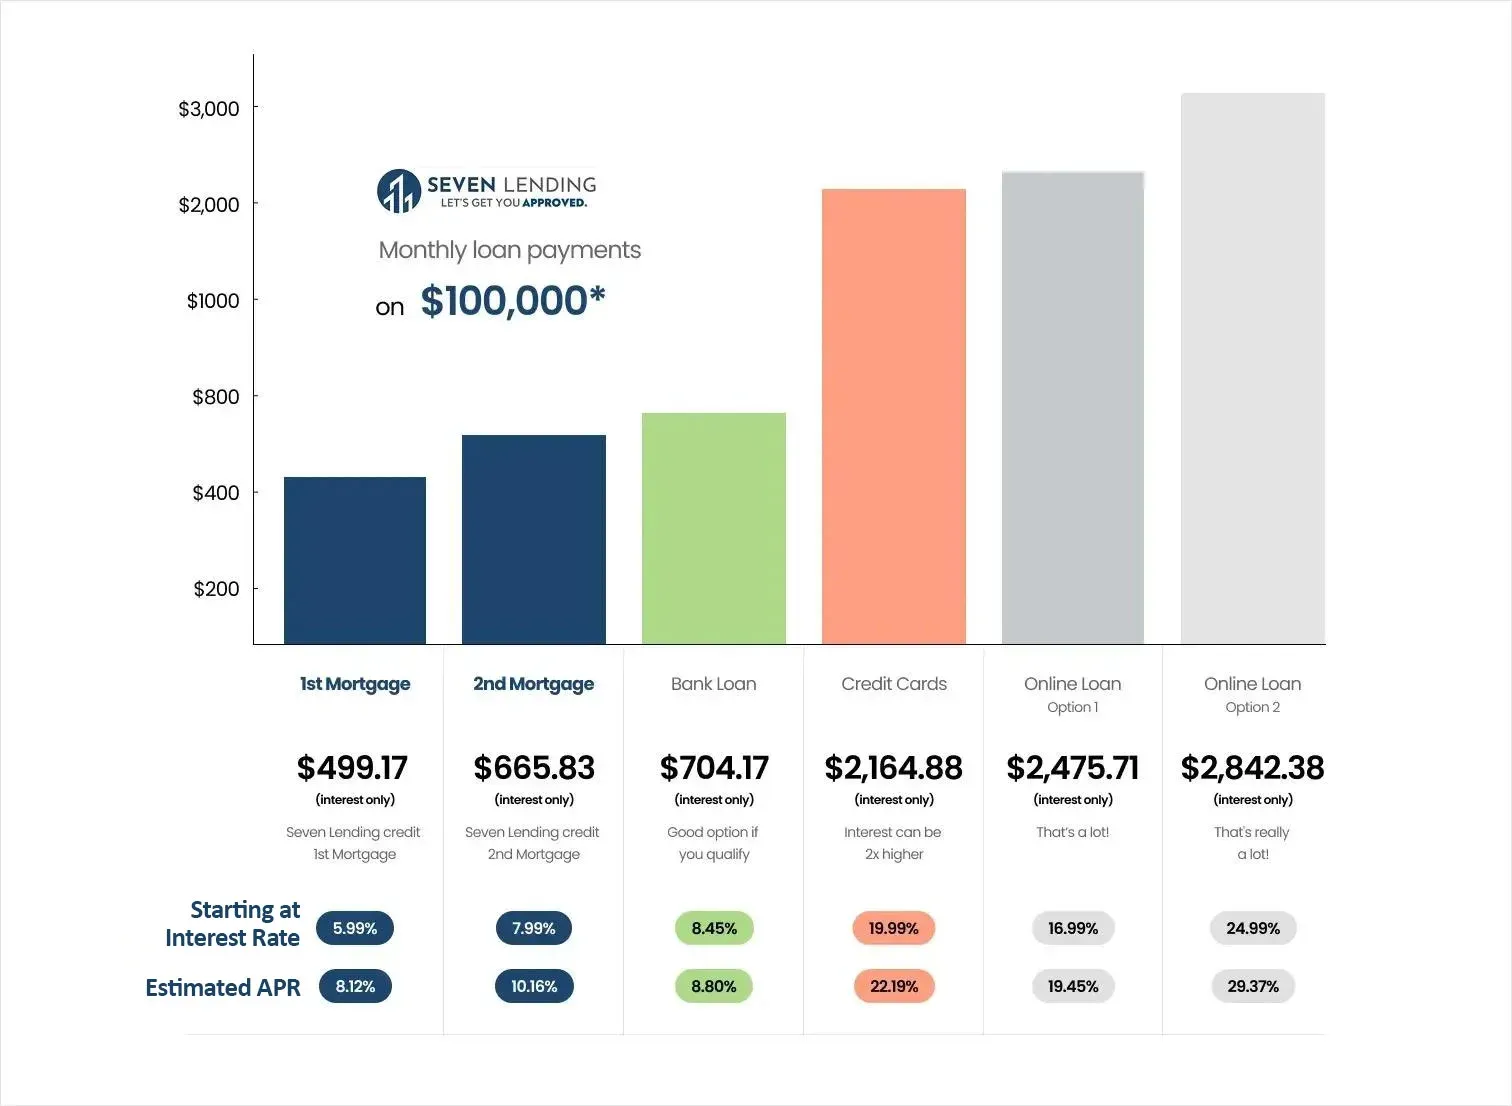
Private mortgage rates and cost comparison for a Kelowna property
Interest and APR The contract rate is only one part of the cost. Review the cost-of-borrowing disclosure with applicable fees.
Lender and service fees Fees can vary by mortgage position, LTV, property type, term, borrower profile, and transaction complexity.
Appraisal and legal work Closing may require an approved appraisal, legal registration, title insurance, payout statements, and discharge work.
Prepayment and renewal Review whether the mortgage is open or closed, what early repayment may cost, and whether an extension needs new approval.
Net funds received The amount available at closing equals the approved mortgage less existing payouts and all disclosed closing deductions.
Enforcement risk A private mortgage is secured by real estate. Missed payments or an unpaid maturity balance can lead to additional costs or enforcement.
Rates, fees, APR, legal expenses, appraisal costs, title insurance, property eligibility, conditions, and final approval vary by file. Review the written mortgage terms and cost-of-borrowing disclosure before closing. Current examples and disclosure notes are maintained on the private mortgage rates page.
Clear mortgage review

Why Choose Seven Lending?

Private mortgage decisions should be supported by clear property evidence, written terms, full cost disclosure, and a practical exit.

Property-Specific Review Strata, investment, construction, recreational, and other properties are reviewed according to their actual risk factors.
First and Second Mortgage Comparison Mortgage position, combined LTV, existing debt, and net proceeds are reviewed before the structure is finalized.
Complex-Income Review Supporting records may include self-employed, contract, commission, rental, or other reasonable income evidence.
Clear Conditions Appraisal, title, insurance, income, payout, and legal requirements should be known before closing.
Total-Cost Explanation Interest, fees, appraisal, legal expenses, payment terms, and maturity obligations should be reviewed together.
Exit Planning Before Funding The refinance, sale, completed project, or another repayment source should be discussed before the short-term mortgage closes.
Local property context

Kelowna and the Wider Central Okanagan

Kelowna proper and the surrounding Central Okanagan can involve different property services, zoning, appraisal evidence, and resale markets.

Kelowna Proper

Neighbourhoods include Downtown, North End, Glenmore, Dilworth Mountain, Rutland, Black Mountain, Lower Mission, Upper Mission, Kettle Valley, and Southeast Kelowna.

  • Urban and suburban strata properties
  • Detached homes and rental suites
  • Investment and redevelopment files
  • Area-specific appraisal comparables

Wider Central Okanagan

West Kelowna, Peachland, Lake Country, and nearby recreational areas can involve different municipalities, property services, access, construction patterns, and resale markets.

  • Recreational and seasonal properties
  • Lake-adjacent and rural locations
  • Construction and renovation projects
  • Different zoning and appraisal evidence
From review to closing

Our Simple 4-Step Process

A private mortgage moves more smoothly when the property, documents, conditions, legal work, and exit plan are organized.

Review the Property and Goal

Share the address, estimated value, mortgage balance, amount required, loan purpose, deadline, and preferred exit.

Prepare the Supporting File

We organize mortgage statements, appraisal details, income support, purchase documents, leases, strata records, or project information as needed.

Review the Written Terms

Review the amount, rate, APR, fees, payment, mortgage position, conditions, prepayment rules, and maturity date.

Complete Closing and Track the Exit

Funding follows after conditions are met. The refinance, sale, or repayment plan should be monitored before maturity.

Borrowing risk

Risks and Exit Strategy

A private mortgage should solve a short-term financing need without creating an unclear maturity deadline.

Payment and Cash-Flow Risk

Interest-only payments may lower the monthly amount, but the full principal can remain due at maturity.

Renewal and Extension Risk

Renewal is not automatic. A delayed refinance, sale, or project can create additional costs or pressure at maturity.

Kelowna private mortgage questions

Frequently Asked Questions

Can a private lender finance a Kelowna strata property?

Possibly. The lender may request strata fees, minutes, depreciation reports, bylaws, insurance, special-assessment details, rental restrictions, mortgage statements, and an appraisal.

Can self-employed borrowers qualify for a private mortgage?

Private lenders may use a broader review than a bank, but they can still request tax records, business statements, bank deposits, contracts, credit history, appraisal information, and a credible exit plan.

Can a recreational property qualify?

Some recreational properties may qualify. The lender reviews access, utilities, water and septic systems, insurance, condition, seasonal use, rental use, appraisal support, and resale market.

Can I get a second mortgage without breaking my first mortgage?

A second mortgage may leave the current first mortgage in place. The lender reviews the first balance, combined LTV, payment history, property value, amount required, and repayment plan.

What are the main risks of a private mortgage?

Private mortgages can include higher interest, lender or service fees, appraisal and legal costs, short terms, prepayment conditions, renewal risk, and enforcement risk if payments or maturity obligations are not met.

Kelowna private mortgage review

Compare a Private First or Second Mortgage

Share the property address, estimated value, mortgage balance, amount required, loan purpose, deadline, income situation, and preferred exit.

The goal is a workable short-term mortgage structure with clear costs, conditions, and a realistic route out.

Start With the Property and the Exit

A private mortgage is secured by real estate. Missed payments or an unpaid maturity balance can lead to added costs or enforcement, so the payment budget and repayment plan must be realistic.

Review the written commitment carefully and obtain independent legal advice before closing.

Read Our Client Success Stories

Meet Our Team

Our team is made up of dedicated professionals who are passionate about helping our clients succeed. We are proud to be your neighbours and your trusted advisors.

Raghav Side Hand Crossed

Raghav Manchanda

Managing Broker

The visionary behind Seven Lending, our Managing Broker oversees all lending operations and ensures regulatory compliance. With a deep understanding of the private mortgage market, he focuses on risk management and strategic growth. He mentors the team while fostering high-level relationships with institutional partners, ensuring every transaction aligns with our core values of integrity and efficiency.

Darius

Darius Hossein-pour

Business Development Manager (BDM)

Our BDM is the primary bridge between Seven Lending and the broker community. He focuses on expanding our network, identifying new market opportunities, and providing creative structuring for complex private deals. Known for his responsiveness and industry insights, he ensures that our lending products meet the evolving needs of our partners and their clients.

Simran

Simran Attili

Mortgage Broker

Our Mortgage Broker is a dedicated client advocate, specializing in custom private lending solutions. She manages the end-to-end application process, expertly navigating unique financial scenarios to secure the best possible terms. By prioritizing clear communication and fast turnaround times, she helps borrowers bridge financial gaps and achieve their real estate goals with confidence.

Gagan Side

Gagandeep Kaur

Mortgage Underwriter

She works with precision and speed. She is responsible for evaluating loan applications, assessing property valuations, and analyzing risk to ensure sound lending decisions. By working closely with brokers and BDM, she streamlines the approval process. For her, underwriting isn’t just about checking boxes—it’s about providing the clarity and speed you need to move forward with your real estate goals.

Pranika

Pranika Khanna

Administrative Assistant & Social Media Coordinator

As the creative spark and organizational anchor of Seven Lending, our Administrative Assistant and Social Media Coordinator ensure our office runs like clockwork while our brand shines online. She is the voice of our digital community, crafting engaging content that demystifies private lending. Whether streamlining logistics for a smooth closing or sharing industry insights, she makes the mortgage process feel less like paperwork and more like a shared success story.

Private Mortgage Lenders in Kelowna | Flexible Loans
Kelowna private mortgage solutions

Private Mortgage Lenders in Kelowna for Flexible Property Financing

Private mortgage lenders in Kelowna may help when a bank cannot approve the property, income, credit profile, timing, or loan purpose under standard rules.

At Seven Lending, we arrange private first and second mortgages for homeowners, buyers, investors, and business owners. We review the property, available equity, mortgage position, loan-to-value ratio, costs, risks, and exit plan before presenting an option.

Kelowna files can involve strata homes, investment properties, self-employed income, construction projects, recreational properties, or short closing deadlines. Each scenario needs a lender that understands the property and repayment route.

  • Private first and second mortgages for short-term needs.
  • Strata, investment, construction, and recreational property review.
  • Clear LTV, costs, risks, conditions, and exit planning.

Private Mortgage Loans in Kelowna

The mortgage structure should match the property, amount required, deadline, mortgage position, and expected repayment source.

Kelowna home reviewed for private first and second mortgage options
Private first mortgages

A private first mortgage can support a purchase, refinance, maturing loan, or property that does not fit conventional lending. It becomes the primary charge on title.

Private second mortgages

A second mortgage sits behind the existing first mortgage. It may release equity without breaking a strong first-mortgage rate or term.

Review how a second mortgage works
Home equity financing

Homeowners may compare a HELOC, fixed home equity loan, second mortgage, or full refinance based on the current first mortgage, amount needed, payment budget, and exit plan.

Compare BC home equity loan options
Bridge financing

Bridge financing may cover a short gap between a purchase and a confirmed sale, refinance, or other repayment event. Clear dates, equity, and a backup route are essential.

Compare a bridge loan with a HELOC
Complex and self-employed income

Business owners, contractors, commission earners, and borrowers with variable income may need tax records, financial statements, bank deposits, contracts, or other reasonable support.

Review self-employed mortgage options
Bad credit or recent credit events

A private lender may consider the property, equity, cause of the credit issue, recent payment history, amount requested, and repayment plan.

Review bad credit mortgage options in BC
Commercial property financing

Retail, office, industrial, mixed-use, and owner-occupied properties are reviewed using value, NOI, leases, zoning, borrower contribution, guarantees, and exit strategy.

Explore commercial mortgage financing

How Can I Use My Kelowna Home Equity?

Home equity is the property’s accepted value minus all secured mortgage balances. The amount available to borrow is lower because the lender applies a maximum LTV and deducts existing debt and closing costs.

A private home equity loan may provide one lump sum for debt consolidation, renovations, a time-sensitive purchase, tax arrears, business needs, or another defined purpose.

  • Keep the first mortgage: A second mortgage may preserve the current first-mortgage rate or term.
  • Replace the first mortgage: A refinance may combine debt into one larger first mortgage.
  • Use revolving credit: A HELOC may suit costs that occur over time, but variable rates can change the payment.
Kelowna homeowner reviewing available property equity and financing choices

Kelowna Property Scenarios We Review

Each property type changes the appraisal, lender pool, conditions, costs, and exit strategy.

S

Strata Properties

Lenders may request strata fees, minutes, depreciation reports, insurance, special-assessment details, bylaws, and rental restrictions.

I

Investment Properties

Leases, market rent, vacancy, legal use, property condition, and the investor’s exit plan can affect the decision. See our investment property mortgage guide.

C

Construction Projects

Plans, permits, budget, builder information, draw schedules, contingency funds, and completion financing may be required. Review construction loan options.

R

Recreational Properties

Seasonal access, water, septic, utilities, rental use, insurance, condition, and resale demand may narrow the lender pool.

Debt Consolidation Through Property Equity

A secured loan may replace several higher-cost debts with one payment, but the debt becomes tied to the property.

%

High Interest Costs

Compare the new secured cost with the debts being paid out, including all lender, brokerage, appraisal, and legal fees.

C

Credit Recovery

A consolidation plan may create room to rebuild payment history, reduce revolving balances, and prepare for a lower-cost refinance.

$

Monthly Cash Flow

A lower monthly payment can help, but a longer repayment period may increase total interest. The budget must also stop paid-out debts from returning.

Loan Position and Loan-to-Value in Kelowna

Mortgage position and LTV help determine the lender’s security, the available loan amount, and the expected cost.

First Mortgage Position

A first mortgage has priority on title. It may pay out the current secured debt and become the main mortgage against the property.

  • Usually a larger security position for the lender
  • May support a purchase or full refinance
  • Breaking the current mortgage may trigger a prepayment charge

Second Mortgage Position

A second mortgage sits behind the first mortgage. The lender reviews the combined balance of both loans against the accepted property value.

  • May preserve the current first mortgage
  • Usually costs more than a first mortgage
  • Needs a clear plan for repayment or refinance
Basic LTV formula: total secured mortgage debt ÷ lender-accepted property value. A lower LTV gives the lender a larger equity cushion, but it does not guarantee approval.

Private Mortgage Costs in Kelowna

Private mortgage pricing is file-specific. Compare the full cost of borrowing instead of relying on one advertised rate.

Private mortgage cost comparison for a Kelowna property

*Interest rates are compounded monthly, not in advance.

*All content is subject to change without notice.

* Terms and conditions apply.

* Final approval is at the sole discretion of the lending committee.

*The APR mentioned here is higher than the rate because it assumes additional costs including lender fee, broker fees and legal fee plus other costs not limited to title insurance, appraisal costs etc. for a 1st or 2nd mortgage offered by Seven Lending.

*Numbers are estimate only and provided to show an illustration, for up-to-date numbers and exact APR please refer to Fixed Credit Disclosures of the offering or contact a licensed agent with Seven Lending.

Interest and APR The contract rate is only one part of the cost. APR may include applicable lender and brokerage fees over the stated term.
Lender and brokerage fees Fees vary by position, LTV, property type, term, borrower profile, and transaction complexity.
Appraisal and legal work Closing may require an approved appraisal, legal registration, title insurance, payout statements, and discharge work.
Prepayment and renewal Review whether the loan is open or closed, what early repayment may cost, and whether renewal would require new approval or fees.
Net funds received The amount available at closing equals the approved loan less existing payouts and every closing deduction.
Enforcement risk A private mortgage is secured by real estate. Missed payments or an unpaid maturity balance can lead to added costs or enforcement.

Current examples and disclosure notes are maintained on our private mortgage rates page. Exact terms come from the written lender commitment.

Why Choose Seven Lending?

Private mortgage decisions should be based on a clear property review, written terms, full cost disclosure, and a practical exit.

Property-Specific Lender Matching

Strata, investment, construction, recreational, and commercial properties are not treated as the same risk.

First and Second Mortgage Comparison

We explain how mortgage position, combined LTV, existing debt, and net proceeds change the structure.

Complex-Income Review

We identify the records that may support self-employed, contract, commission, rental, or business income.

Clear Lender Conditions

You receive a practical list of appraisal, title, insurance, income, payout, and legal items required for closing.

Total-Cost Explanation

The review covers interest, APR, fees, appraisal, legal costs, payment terms, and maturity obligations.

Exit Planning Before Funding

The refinance, sale, construction completion, or other repayment source is discussed before the short-term loan closes.

Kelowna and the Wider Central Okanagan

Kelowna proper and the surrounding Central Okanagan should not be treated as one identical property market.

Kelowna Proper

Kelowna neighbourhoods include Downtown, North End, Glenmore, Dilworth Mountain, Rutland, Black Mountain, Lower Mission, Upper Mission, Kettle Valley, and Southeast Kelowna.

  • Urban and suburban strata properties
  • Detached homes and rental suites
  • Investment and redevelopment files
  • Area-specific appraisal comparables

Wider Central Okanagan

West Kelowna, Peachland, Lake Country, and nearby recreational areas can involve different municipalities, property services, access, construction patterns, and resale markets.

  • Recreational and seasonal properties
  • Lake-adjacent and rural locations
  • Construction and renovation projects
  • Different zoning and appraisal evidence

Our Simple 4-Step Process

A private mortgage can move smoothly only when the property, documents, lender conditions, legal work, and exit plan are organized.

Four-step private mortgage process for a Kelowna property
1

Review the Property and Goal

Share the address, estimated value, mortgage balance, amount required, loan purpose, deadline, and preferred exit.

2

Prepare the Supporting File

We organize title, mortgage statements, appraisal details, income support, purchase documents, leases, strata records, or project information as needed.

3

Compare the Written Terms

Review the amount, rate, APR, fees, payment, mortgage position, conditions, prepayment rules, and maturity date.

4

Complete Closing and Track the Exit

The lender funds after all conditions are met. The refinance, sale, or repayment plan should be monitored before maturity.

Risks and Exit Strategy

A private mortgage should solve a short-term problem without creating an unclear maturity deadline.

Payment and Cash-Flow Risk

Interest-only payments may lower the monthly amount, but the full principal can remain due at maturity.

Renewal and Extension Risk

Renewal is not automatic. A delayed refinance, sale, or project may lead to new fees, a higher rate, or pressure at maturity.

Exit Strategy

The plan may be a refinance, property sale, completed construction, improved income documentation, debt reduction, or another confirmed source.

A detailed private mortgage exit strategy should include target dates, required improvements, expected costs, and a backup route.

Frequently Asked Questions

Can a private lender finance a Kelowna strata property?

Possibly. The lender may request strata fees, minutes, depreciation reports, bylaws, insurance, special-assessment details, rental restrictions, mortgage statements, and an appraisal.

Can self-employed borrowers qualify for a private mortgage?

Private lenders may use a broader review than a bank, but they can still request tax records, business statements, bank deposits, contracts, credit history, appraisal information, and a credible exit plan.

Can a recreational property qualify?

Some recreational properties may qualify. The lender reviews access, utilities, water and septic systems, insurance, condition, seasonal use, rental use, appraisal support, and resale market.

Can I get a second mortgage without breaking my first mortgage?

A second mortgage may leave the current first mortgage in place. The lender reviews the first balance, combined LTV, payment history, property value, amount required, and repayment plan.

What are the main risks of a private mortgage?

Private mortgages can include higher interest, lender and brokerage fees, appraisal and legal costs, short terms, prepayment conditions, renewal risk, and enforcement risk if payments or maturity obligations are not met.

Kelowna private mortgage review

Compare a Private First or Second Mortgage

Share the property address, estimated value, mortgage balance, amount required, loan purpose, deadline, income situation, and preferred exit.

We will identify the likely lender categories, expected documents, costs, conditions, and repayment requirements. The goal is a workable short-term structure with a clear route out.

Start With the Property and the Exit

A private mortgage is secured by real estate. Missed payments or an unpaid maturity balance can lead to added costs or enforcement, so the payment budget and repayment plan must be realistic.

Review the written commitment carefully and obtain independent legal advice before closing.

What Our Clients Say
Apply Now

*After submitting this form, we will contact you within 24 hours.

Start with Seven Lending. We Are Here For You!

*After submitting this form, we will contact you within 24 hours.

Start with Seven Lending. We Are Here For You!

*After submitting this form, we will contact you within 24 hours.